5 Minute Bank Feed Integration for EU Teams

A bank feed integration is a read-only, automated connection that delivers transactions and balances from bank accounts into accounting software so reconciliation happens without manual entry. The most reliable approach for European teams is a read-only Open Banking connection, either built directly against PSD2 APIs or run through a vendor-managed bank sync, that pushes daily statements into your accounting system. Done properly, it gives you live balances, automatic reconciliation and far less manual bookkeeping work.
TL;DR:
- European teams should focus on using a read-only Open Banking connection to ensure daily statement updates and reliable automatic reconciliation.
- Proper implementation involves managing API token lifecycle, batching data, and transforming bank-specific fields into a standard internal schema.
- Building a PSD2-compliant bank feed requires careful handling of authentication, consent renewal, and account mapping to prevent balance mismatches.
- Testing should prioritize balance accuracy, duplicate handling, and multi-currency conversions before scaling and deploying live feeds.
- Using a vendor solution like Zenith can drastically reduce development time, offering quick setup and extensive bank coverage across Europe.
Table of Contents
- What a bank feed is and how the data actually flows
- How bank feeds work technically: APIs, connectors and endpoints
- Authentication, PSD2 and SCA: what to design for
- Data model and mapping: transactions, balances and statement periods
- Implementation checklist and step-by-step integration plan
- Testing, reconciliation and bookkeeping best practices
- Production concerns: idempotency, batching, monitoring and security
- How Zenith fits into a bank sync build
- What the checklist gets wrong for most teams
- Getting bank sync running without the build
- Sources
- FAQ
What a bank feed is and how the data actually flows
A bank feed sits between a bank account and your accounting ledger, moving transaction and balance data automatically instead of relying on someone uploading a CSV or typing figures in by hand. In a bookkeeping workflow, it is the layer that keeps your ledger’s cash position honest day to day.
Technically, the flow runs from the bank (the ASPSP, or account-servicing payment service provider) through an AISP or connector that holds the Open Banking consent, into a normaliser that reshapes the bank’s raw statement format, and finally into the accounting platform’s API. Some accounting platforms expose a pull model where your connector fetches statements on a schedule; others expect a push, where you send transactions to a feed endpoint as soon as they exist. Choose pull when you control the polling cadence and want predictable load, and push when the accounting platform’s feed API is built for near-real-time updates and you already have a queue in place.

How bank feeds work technically: APIs, connectors and endpoints
A working connector typically implements four API resources: creating a connection to the bank, linking specific accounts, mapping those accounts to the correct ledger or bank-feed account in the accounting system, and uploading statements or individual transactions, as explained in Direct deposit automation for banks and fintech — Glendale Payroll.
Behind those endpoints, the connector carries three ongoing responsibilities. It manages the token lifecycle, refreshing access tokens before they expire and handling revocation gracefully. It batches data sensibly rather than firing one API call per transaction, and it transforms bank-specific fields (dates, references, counterparties) into a consistent internal schema before anything reaches the accounting API.
Accounting platforms differ in how they expose feeds. Some accept whole statement objects with an opening and closing balance; others want discrete transaction records and calculate balances themselves. A well-built connector abstracts this difference so the rest of your system deals with one internal format, letting you add a new accounting target without rewriting your ingestion logic. Unified-API providers such as Apideck take exactly this approach, standardising connector behaviour so a single integration can serve multiple accounting platforms, cutting the build from months to weeks.
Authentication, PSD2 and SCA: what to design for
PSD2 governs how third parties access account data, and its Regulatory Technical Standards on Strong Customer Authentication set the exemption rules your consent flow must respect. Under Delegated Regulation (EU) 2022/2360, the SCA renewal window for AISP access was extended from the earlier 90-day practical expectation to 180 days in many cases, meaning a user does not have to re-authenticate as often to keep a feed running. The EBA’s final report on the RTS amendment sets out the safeguards behind that exemption and confirms that an ASPSP can still demand more frequent SCA where it has evidence of fraud risk, regardless of the 180-day allowance.
Design for that variability rather than assuming a fixed schedule. Build a consent renewal flow that can trigger early, give users a clear re-authentication path inside your product rather than an error message, and keep a contingency mechanism (a fallback access route) ready for banks that have not fully implemented their dedicated interface. Our guide to Open Banking and security practices covers the consent-UX side in more detail.
Data model and mapping: transactions, balances and statement periods
Reconciliation lives or dies on a small set of fields: transaction date, amount, currency, counterparty reference, and the statement’s opening and closing balance. Miss any of these and your accounting platform’s balance check will fail, because Xero’s own bank feed documentation treats automatic balance alignment as the baseline expectation for a working feed.
Chronology matters as much as the fields themselves. Statements must arrive in order, with no gaps or overlapping periods, or the closing balance of one statement will not match the opening balance of the next. Multi-currency accounts add a further wrinkle: convert consistently at the transaction level, not the batch level, and expect small FX rounding differences that your reconciliation logic needs to tolerate rather than flag as errors every time.
Implementation checklist and step-by-step integration plan
Shipping a bank feed reliably follows a predictable sequence rather than a single big build.
- Prepare: decide whether to build directly against bank APIs or use a vendor-managed connector, map your target accounting fields, and get sandbox access from both the bank and the accounting platform.
- Build: implement the auth flow, account linking, a normalisation layer for incoming data, and a sender service that batches or streams transactions into the accounting API.
- Test before production: verify balance alignment on every statement, check duplicate detection, and run edge cases such as backdated transactions and partial imports.
- Deploy and run: set a sensible polling or push cadence, monitor auth failures, rotate credentials on schedule, and keep a support playbook for when a bank changes its interface.
Teams weighing build versus buy at step one should see our comparison of direct bank APIs against a managed sync before committing engineering time.
Pro Tip: Run your first two weeks of live statements in parallel with your existing manual process before switching over entirely, so a mapping error shows up in a side-by-side comparison rather than in your closing accounts.
Testing, reconciliation and bookkeeping best practices
Test balances before you test anything else. If the closing balance on a pushed statement does not match what the bank reports, nothing downstream can be trusted, no matter how clean the transaction list looks.
- Never edit a historical transaction that has already been pushed; send a correcting statement instead, since accounting platforms validate closing balances and typically reject direct edits to past entries.
- Test duplicate submissions deliberately, including the same statement sent twice after a retry.
- Test date-shifted transactions, where a bank reports a transaction a day later than the account holder expects.
- Test partial imports, where a batch fails halfway through, to confirm nothing gets double-counted on retry.
- Test multi-currency statements for rounding drift across a full accounting period.
Pair this with ongoing tooling: a daily reconciliation report comparing bank-reported balances to ledger balances, webhook alerts on failed pushes, and a review workflow for anything flagged before it reaches the finance team.
Production concerns: idempotency, batching, monitoring and security
Idempotency is the single most important production safeguard. Give every statement and transaction a unique, stable ID so a retried upload never creates a duplicate entry, however many times a network failure forces a resend.

Batch size is a trade-off: large batches reduce API call volume but mean a single malformed record can block an entire statement, while smaller batches isolate failures at the cost of more calls and a higher chance of hitting rate limits. Build retries with backoff rather than immediate resubmission.
Monitor auth failures, balance mismatches and missed sync windows as first-class alerts, not silent log entries, and keep an audit log of every statement pushed. Store credentials in a secrets manager, request read-only scopes wherever the bank offers them, and never persist raw account credentials in application logs.
How Zenith fits into a bank sync build
For teams that would rather not build and maintain PSD2 connectors themselves, Zenith’s bank sync provides a read-only PSD2 connection across 2,400+ banks in 30 European countries, delivering data to Google Sheets, Claude (MCP), a REST API or CSV. Setup takes around 5 minutes, pricing is €5 per account/month, and it carries a 30-day money-back guarantee. A vendor connection removes the ongoing work of token refresh and bank-specific quirks, but you still own the mapping into your own ledger and reconciliation logic. Technical details are in the developer documentation.
What the checklist gets wrong for most teams
Most guidance on this topic treats PSD2 compliance and the developer build as separate problems, one for legal, one for engineering. That split is where projects actually fail. The 180-day SCA window is a regulatory ceiling, not a design target, and an ASPSP can still force re-authentication whenever it judges the risk warrants it. Teams that hard-code a 180-day renewal assumption end up with support tickets when a bank behaves differently.
The more overlooked risk is on the accounting side, not the banking side. Developers spend weeks hardening the PSD2 connection and then push transactions with a normalisation layer that was never tested against the accounting platform’s own balance validation, which is exactly where statements get silently rejected. Balance-first testing should come before feature completeness, not after.
If you are choosing where to spend limited engineering time, spend it on the normalisation and reconciliation layer, not on the bank connection itself. A vendor-managed sync removes most of the PSD2 complexity for you. Nobody removes the job of getting your own ledger mapping right.
— Gašper Anderle
Getting bank sync running without the build
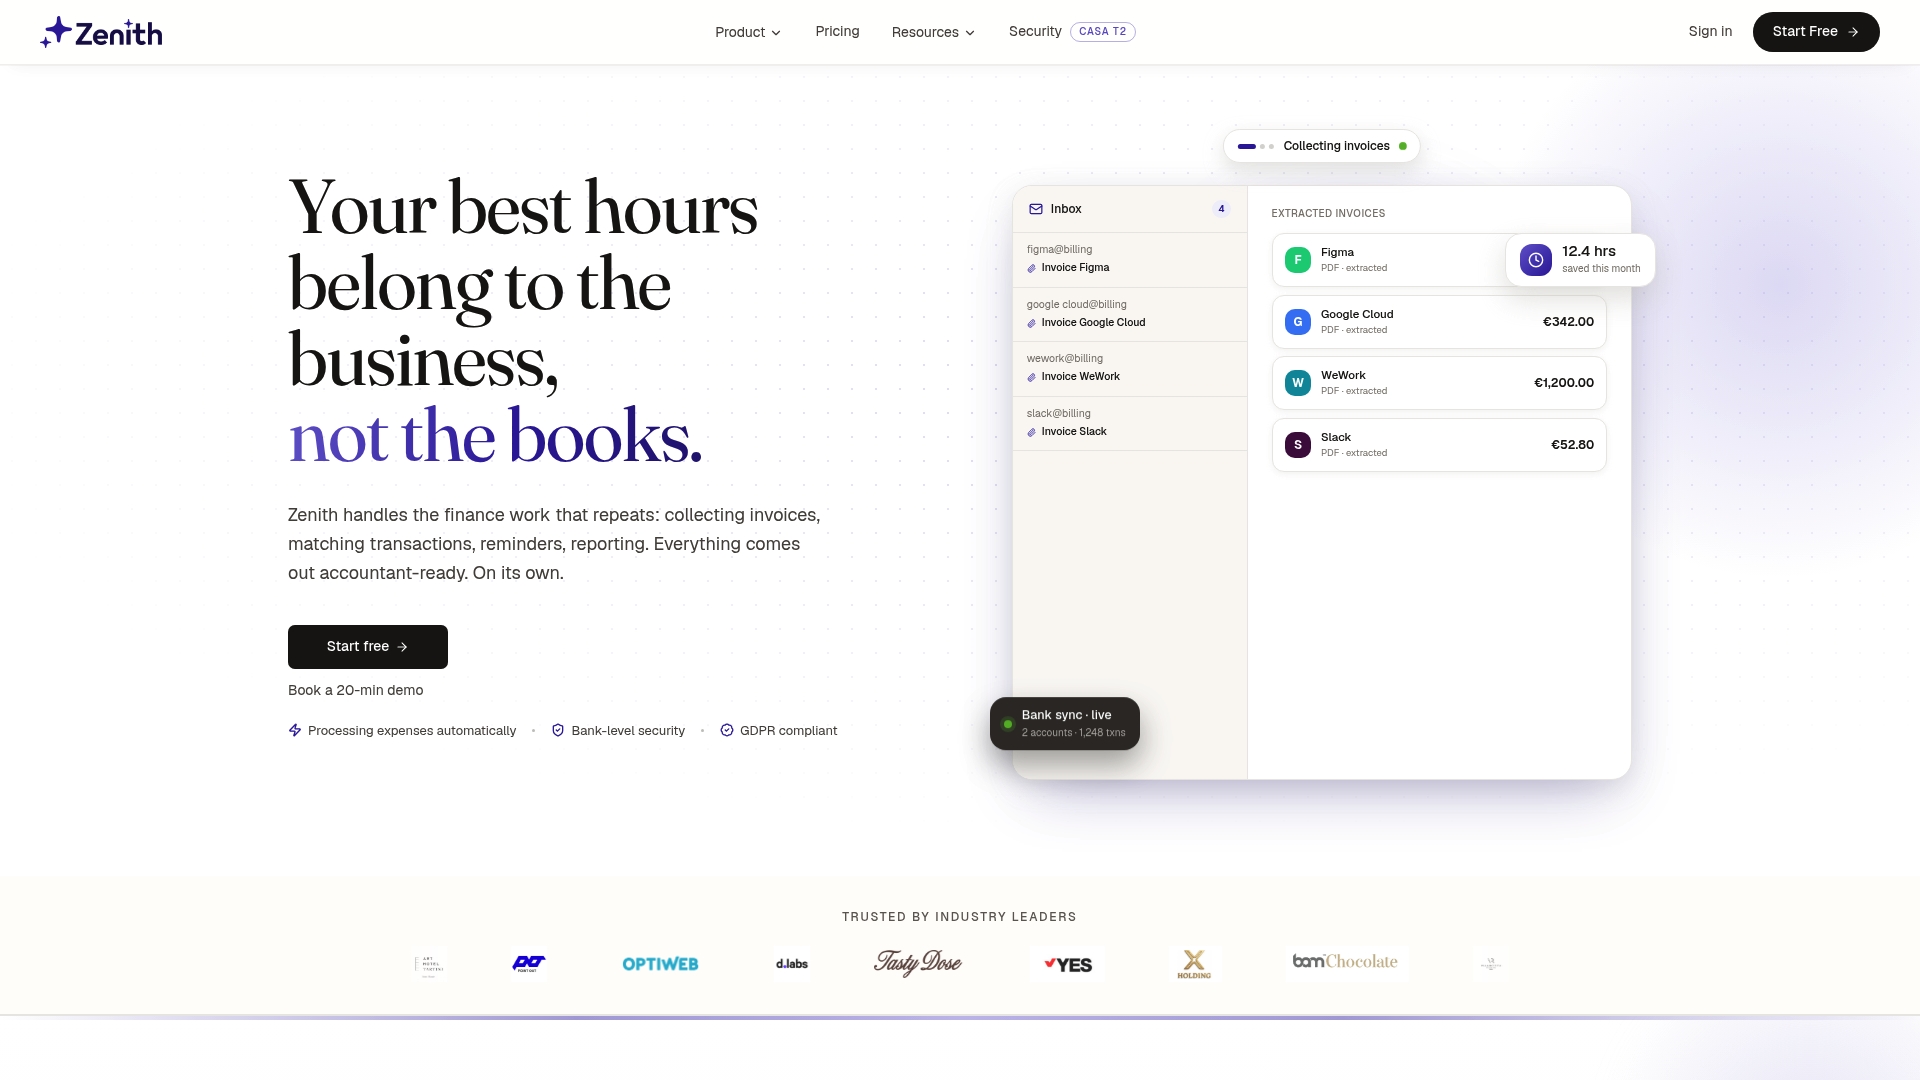
If building and maintaining PSD2 connectors for every bank your customers use is not where you want to spend engineering time, Zenith’s bank sync gives you the same read-only connection, coverage and delivery formats described above, with a 5-minute setup and no long-term contract beyond the monthly account fee.
| What you get | Detail |
|---|---|
| Coverage | 2,400+ banks across 30 European countries |
| Delivery formats | Google Sheets, Claude (MCP), REST API, CSV |
| Setup time | 5 minutes |
| Price | €5 per account/month |
| Guarantee | 30-day money-back guarantee |
Plans and pricing, including Free & Pay-as-you-go, Starter, Growth and Business tiers, are listed on the pricing page. Start on the free plan to connect an account and see the feed running before committing to a paid tier.