Table of Contents
- Why Automate Bank Reconciliation
- What You'll Need Before You Start
- Step 1: Connect Your Bank Account to Your Accounting System
- Step 2: Set Up Automated Reconciliation Tools
- Step 3: Configure Rules and Match Transactions Automatically
- Bank Reconciliation Best Practices for Automation
- Reconciling Bank Statements in Google Sheets
- Common Mistakes to Avoid When Automating Reconciliation
- Frequently Asked Questions
Last Updated: October 3, 2026
Why Automate Bank Reconciliation
Bank reconciliation is the process of matching transactions in your accounting system to those on your bank statement. It catches errors, prevents fraud, and ensures your financial records are accurate. Manually reconciling bank accounts eats up hours every month. For businesses with multiple accounts or high transaction volumes, the time drain becomes unsustainable. (Source: the benefits of automation in finance)
Automating bank reconciliation eliminates this burden. Instead of downloading CSV files, comparing line items, and chasing discrepancies manually, the system handles matching automatically. Transactions sync in real time. Discrepancies flag instantly. Your team moves from data entry to analysis and decision-making.
The real benefit isn't just time saved. Automated reconciliation reduces human error, improves cash visibility, and ensures month-end closes happen faster. Finance teams stop firefighting and start forecasting.
What You'll Need Before You Start
Before you set up automated bank reconciliation, gather these essentials:
- A compatible accounting system (QuickBooks, Xero, FreshBooks, or similar)
- Bank login credentials for the accounts you want to reconcile
- API access or open banking connection to your bank
- Permission from your bank to share transaction data
- A clear reconciliation process documented (what counts as a match, how to handle exceptions)
Your accounting software is the foundation. Most modern systems have built-in reconciliation features or integrations with bank data providers. Check if your software already connects to your bank through open banking standards like PSD2 (Payment Services Directive 2) in Europe.
Open banking APIs like Zenith connect to over 2,400 banks across 30 European countries. They pull live transaction data directly into your accounting system, Google Sheets, or custom tools without manual CSV downloads.
Review your current process first. Document which accounts need reconciling, how often, and what rules govern matching transactions. This clarity makes automation setup faster and more effective.
Step 1: Connect Your Bank Account to Your Accounting System
The first step is establishing a secure connection between your bank and your accounting software. Most banks now support open banking connections through PSD2 or similar standards. This means you authenticate once through your bank's own login portal, not by sharing credentials with a third party.
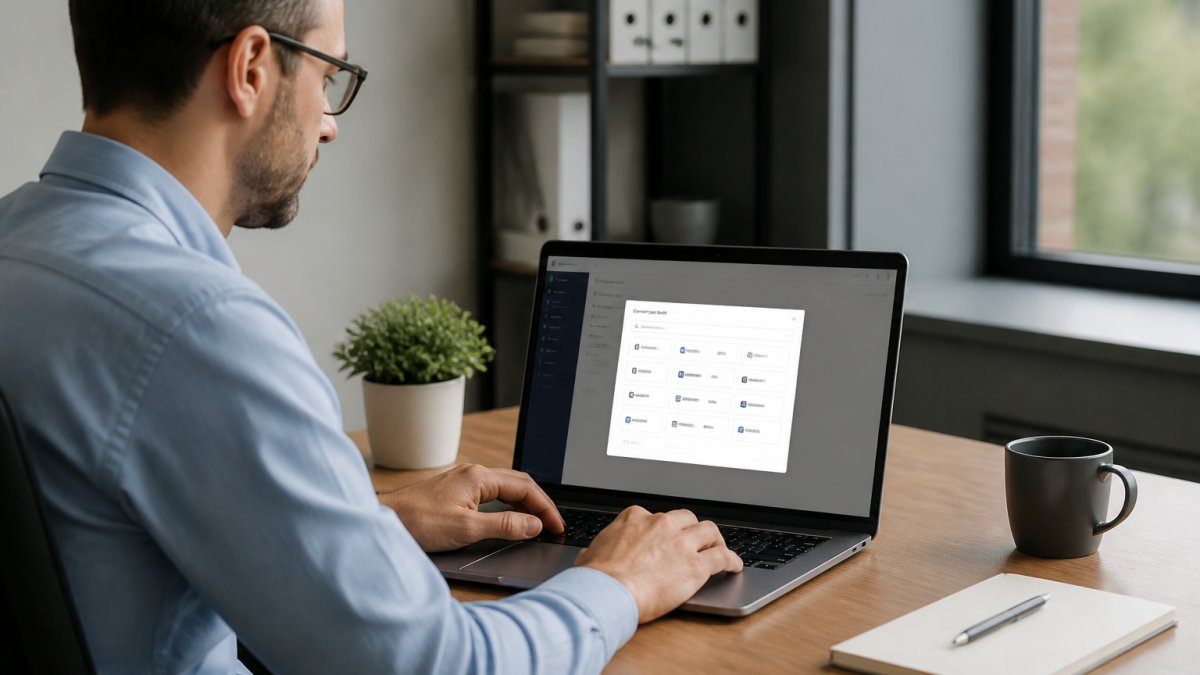
Here's how the process typically works:
- Log into your accounting software and find the bank connections or integrations section
- Select your bank from the available list
- Click "Connect" or "Authorise"
- You'll be redirected to your bank's login page
- Authenticate using your normal bank credentials
- Approve the connection (you control which accounts and data types to share)
- The system confirms the connection and begins syncing data
This flow is secure because your bank handles authentication directly. Your accounting software never stores your login credentials. You can revoke access anytime through your bank's settings.
If your bank isn't listed in your accounting software's integration library, you may need to use a dedicated bank data provider. Zenith, for example, connects to thousands of European banks and pushes transaction data into Google Sheets, APIs, or accounting platforms via direct integration. This gives you flexibility if your bank isn't natively supported.
Step 2: Set Up Automated Reconciliation Tools
Once your bank is connected, configure the reconciliation rules within your accounting software. Most systems let you define how transactions should match automatically.
Common matching rules include:
- Amount matching: Transactions with identical amounts are paired
- Date matching: Transactions dated within a set window (e.g., 3 days) are considered potential matches
- Reference matching: Transactions with matching invoice or reference numbers are linked
- Payee matching: Transactions from the same vendor or customer are grouped
- Description matching: Keywords in transaction descriptions trigger automatic pairing
Set up rules that reflect your actual workflow. If most of your transactions are invoices with reference numbers, prioritise reference matching.
Test your rules on a small batch first. Run a test reconciliation on your last month of transactions. Check how many matched automatically versus manually.
Many businesses find that starting with basic rules (amount plus date) catches 70-85 percent of transactions. Adding reference or invoice number matching pushes automation to 90 percent or higher.
Step 3: Configure Rules and Match Transactions Automatically
This step is where automating bank reconciliation truly takes effect. You're teaching the system to recognise and pair matching transactions without human intervention.
Most accounting software lets you create rule sets with multiple conditions. Here's a practical approach:
Rule 1: Exact match
- Amount equals bank transaction amount
- Date is within 1 day
- Result: Auto-reconcile
Rule 2: Fuzzy match
- Amount equals bank transaction amount
- Date is within 3 days
- Payee name contains keywords from your vendor list
- Result: Flag for review (not auto-reconcile)
Rule 3: Multi-transaction match
- Bank deposit amount equals sum of multiple invoices
- Dates overlap by up to 5 days
- Result: Link transactions and flag for confirmation
Configure exceptions separately. For example, bank fees, interest, and transfers often need manual review because they don't match invoice amounts.
After setting rules, run a full reconciliation on your historical data. The system will match what it can and flag exceptions. Review flagged items to understand why they didn't match.
Once you're confident in your rules, enable automatic reconciliation for ongoing transactions. Most systems process new bank data daily or weekly, depending on your bank's sync frequency.
Bank Reconciliation Best Practices for Automation
Successful automation depends on clean data and consistent processes. Here are practices that make automated reconciliation work reliably:
Keep your chart of accounts organised. Each bank account should map to a single GL account. Avoid reconciling multiple bank accounts to one GL account, as this creates ambiguity for the matching engine.
Use consistent invoice numbering. If your invoicing system generates reference numbers, include them in bank transaction descriptions when possible.
Reconcile frequently, not monthly. Daily or weekly reconciliation catches errors early. Monthly reconciliation means problems compound over 30 days. Automation makes frequent reconciliation practical.
Document your rules. Write down why each rule exists and what it's designed to catch.
Monitor exception reports. Automated systems flag unmatched transactions. Review these regularly.
Separate cash and accrual reconciliation. If you use accrual accounting, reconcile bank deposits separately from invoiced revenue.
Automation handles routine matching, but human oversight remains essential. Your role shifts from matching transactions to validating the system's work and investigating exceptions.
Reconciling Bank Statements in Google Sheets
Not all businesses use traditional accounting software.
Zenith and similar open banking providers can push transaction data directly into Google Sheets. Once data flows into a sheet, you can use formulas to match transactions automatically.
Here's a basic approach:
Step 1: Import bank transactions Set up a connection to pull bank transactions into a "Bank Feed" sheet. Include columns for date, amount, description, and reference number.
Step 2: Import GL transactions Create a separate sheet with your accounting entries. Include the same columns: date, amount, description, reference.
Step 3: Create a matching formula Use a combination of INDEX, MATCH, and SUMIF functions to find matching transactions. For example:
=IFERROR(INDEX(GLsheet!$A$2:$A$100,MATCH(1,(GLsheet!$B$2:$B$100=Banksheet!B2)*(GLsheet!$C$2:$C$100=Banksheet!C2),0)),"No Match") This formula looks for a GL transaction with matching amount and date, returning the reference number if found.
Step 4: Review exceptions Any row without a match will show "No Match". Review these manually to understand why they didn't pair.
Step 5: Mark reconciled transactions Add a "Reconciled" column. Check off transactions that matched successfully.
This approach works well for small businesses or teams that prefer spreadsheets. The downside is manual formula maintenance and limited scalability.
For growing teams, moving to dedicated accounting software with built-in bank reconciliation is more efficient long term.
Common Mistakes to Avoid When Automating Reconciliation
Even well-intentioned automation efforts stumble when certain pitfalls aren't addressed.
Mistake 1: Automating without cleaning data first Dirty data (missing invoice numbers, inconsistent vendor names, duplicate entries) causes matching failures.
Mistake 3: Ignoring exceptions Automated systems flag unmatched transactions as exceptions.
Mistake 4: Reconciling at the wrong frequency Monthly reconciliation is traditional but inefficient.
Mistake 5: Not documenting your process If only one person understands your reconciliation rules and process, you're vulnerable to disruption.
Mistake 7: Trusting automation blindly Even sophisticated matching engines make mistakes. Allocate time for human review. Automated doesn't mean unsupervised.
Automating bank reconciliation transforms how finance teams work.
At Zenith, we've built bank reconciliation automation into our core offering. Zenith Bank Sync connects to over 2,400 European banks and pushes live transaction data into your accounting system, Google Sheets, or API. Combined with invoice OCR and accounts payable automation, Zenith handles the full month-end workflow in one platform. Start Free and see how automated reconciliation simplifies your financial operations.
Frequently Asked Questions
What are the main benefits of automating bank reconciliation?
Automated bank reconciliation eliminates hours of manual data entry each month, reduces human error in transaction matching, and frees your finance team to focus on analysis rather than administrative tasks. You get real-time visibility of your bank balances, faster month-end closes, and accountant-ready financial data without chasing CSV downloads or manual statement reviews.
Can you automate bank reconciliation in Google Sheets?
Yes. You can pull live bank transactions directly into Google Sheets using an open banking API, then set up automated formulas or scripts to match transactions against your records. This works particularly well for smaller operations or teams already working in Sheets, though you'll need to establish clear matching rules and review unmatched items regularly.
How do I choose the right automated reconciliation tools for my business?
Look for tools that integrate with your existing accounting software, support the banks and countries you operate in, and offer the level of automation you need. Consider whether you need AI-powered matching, multi-currency support, or the ability to pull data into spreadsheets. Check that the tool provides read-only access to your bank data and complies with your security requirements.
What's the difference between rules-based and AI-driven reconciliation?
Rules-based reconciliation matches transactions using fixed criteria you set (e.g., amount and date must match exactly). AI-driven reconciliation learns from your matching patterns and can identify matches even when amounts differ slightly or descriptions don't align perfectly, reducing the number of manual exceptions you need to review.